NJ Concrete & Masonry Insurance
Decorative, structural, restoration. Sidewalks and driveways are one profile; commercial structural pours are another; masonry restoration on historic buildings is a third.
Who NJ Concrete & Masonry Insurance Is For
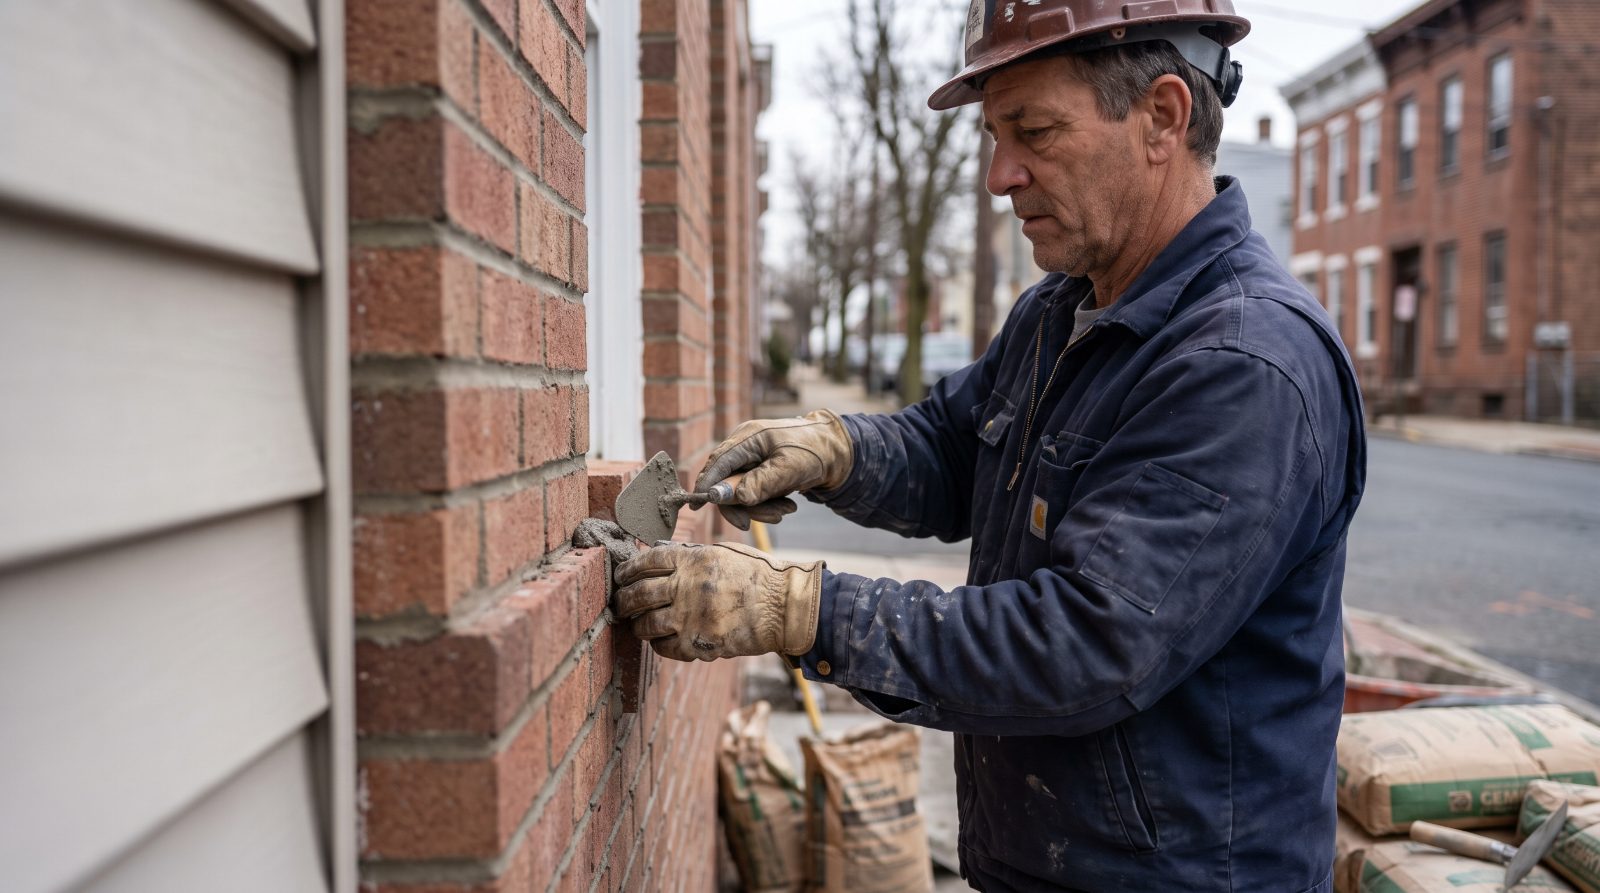
NJ Concrete & Masonry Insurance from NJ Contractors Insurance Center quotes General Liability, Workers Comp, Commercial Auto, Tools and Umbrella in one intake. Decorative concrete (stamped, polished), residential structural (foundations, slabs), commercial structural, brick/block masonry, stone masonry, and historic restoration operations.
Carriers That Write NJ Concrete & Masonry Insurance
Standard panel: Travelers, The Hartford, Nationwide, AmTrust, Cumberland Mutual, Merchants Mutual. Decorative and residential structural is broad market. Commercial structural and historic restoration narrower — but still placeable in standard.
What NJ Concrete & Masonry Insurance Covers
- GL — $1M/$2M standard. Property damage from forming, pours that fail, adjacent property damage during demolition or excavation.
- Workers Comp — required for any employee in NJ. Class codes matter — we audit them at quote.
- Commercial Auto — pickups, dump trailers, sometimes mixer trucks (different conversation if you operate ready-mix).
- Tools & Equipment — forms, vibrators, finishing tools, saws, mixers.
- Commercial Umbrella — recommended; sits over GL, Auto, and EL.
NJ Concrete & Masonry Insurance: NJ-Specific Considerations
- Adjacent property damage on tight urban pours is a common claim source.
- Underground utility damage during excavation/footing work — same XCU consideration as excavation contractors.
- Decorative finishes — products-completed exposure on stamped/colored work that fades or cracks.
- Historic masonry restoration — careful underwriting around the substrate condition and assumed responsibility.
Common questions.
Solo decorative concrete operator — program cost?
Underground utility hit during footing dig — covered?
Stamped concrete patio fading 4 years later — covered?
Commercial structural — different placement?
Historic masonry restoration — can you write it?
Quote your concrete & masonry program in one intake.
GL, WC, Auto, Tools, Umbrella — all in one form. We come back with a multi-line quote, not six separate quote events.